QUARTERLY FINANCIAL RESULTS
LEXICON BANCORP REPORTS CONSOLIDATED FINANCIAL RESULTS AS OF AND FOR THE THREE & NINE MONTHS ENDED SEPTEMBER 30, 2026
Key Highlights
- Net income of $3.9 million year-to-date, up $788 thousand or 25.4% for the nine months ended September 30, 2025
- Loans, net of fees, grew to $205.2 million, up $14.0 million or 7.3% year-over-year
- Opened over 200 new deposit accounts during the quarter, contributing to 2.8% year-over-year deposit growth
- Total assets increased to $457.2 million, up $15.8 million or 3.6% from last year
- On-balance sheet liquidity remains strong quarter-to-quarter with cash and cash equivalents of $220.9 million, an increase of $6.0 million or 2.8%.
- Book value per share grew to $14.81, up 15.91% year over year
- ROAA increased from 1.07% at September 30, 2025 to 1.12% at September 30, 2026, a 4.3% improvement year-over-year
- ROAE increased from 13.59% at September 30, 2025 to 14.05% at September 30, 2026
- The SBA Lending Division originated loans totaling $11.6 million in the first three quarters of 2026, resulting in a net gain on sale of $473 thousand year-to-date. Loans sold were $1.0 million in the third quarter with a net gain on sale for the quarter of $58 thousand
Lexicon Bancorp (“Bancorp”), the parent company for Lexicon Bank (“Bank”) (collectively, “the Company” or “Lexicon”), announces unaudited consolidated financial results as of and for the three, six and nine months ended September 30, 2026, and 2025. Lexicon continues to focus on personalized concierge banking services for its clients, as reflected in the year-over-year increase in both total loans and deposits.
A Message from Our President & CEO
As we approach the close of another successful year, I am encouraged by Lexicon's continued progress and the opportunities ahead. Our year-over-year performance reflects our organization's strength, supported by sustained profitability, a strong liquidity position, and growth across key areas of our business. We recognize that sustainable growth requires both ambition and discipline, and we remain committed to making thoughtful decisions that strengthen the Bank, protect our financial foundation, and create lasting value for our shareholders.
Throughout the year, we have continued to expand our lending capabilities and deepen relationships with businesses and nonprofit organizations across the communities we serve. Our SBA Lending Division is an important part of that progress, broadening our reach and creating new opportunities to support business owners locally and nationally. Combined with our commercial banking efforts, these capabilities support our strategy to diversify revenue opportunities, strengthen earnings potential, and drive future growth.
We are also proud to have earned our 19th consecutive BauerFinancial 5-Star Superior rating, an independent recognition of the financial strength, stability, and prudent management that remain central to our strategy. This achievement reflects our team's dedication and reinforces the sound financial foundation on which we continue to build shareholder value.
As we look toward 2027, our priorities are clear. We are focused on translating our investments in people, capabilities, and relationships into measurable results, while maintaining the financial discipline needed to deliver sustainable returns. I am confident in our strategy, the strength of our team, and our ability to execute on the opportunities ahead. To our shareholders, thank you for your continued trust and investment in Lexicon. We remain committed to building an institution worthy of that confidence and delivering value for years to come.
Unaudited Consolidated Financial Results
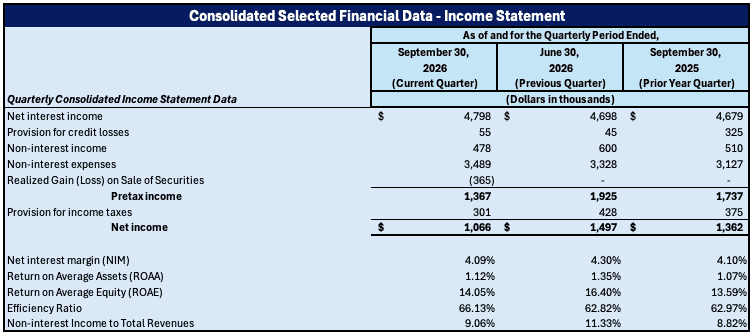
For the period ended September 30, 2026, net income was $3.9 million year-to-date and $1.1 million for the quarter. Net income decreased $431 thousand compared to the quarter ended June 30, 2026. The overall decrease in net income was driven by the following key changes:
- Realized loss on sale of securities of $365 thousand. The loss was a result of a strategic decision to improve the long-term performance of the securities portfolio. The sale was approved by the Board and executed in September 2026. The Bank sold six securities with an average book yield of 1.58% and an average life of 7.67 years and replaced them with securities at an average book yield of 4.58% and an average life of 1.63, which will significantly improve future interest earned on investments.
- Non-interest income decreased by $122 thousand, driven largely by a $155 thousand quarter over quarter decline in SBA loan sales due to the timing of the loan disbursements. This decrease was partially offset by an additional $113 thousand in earnings from the Bancorp’s noncontrolling equity investment in IconTrust, a Las Vegas-based trustee services provider.
- Increased non-interest expenses by $161 thousand, attributable to increased salaries and benefits and an increase in technology costs related to new initiatives.
- Partially offset by an increase in net interest income of $100 thousand due to increased income from total cash and cash equivalents.
Lexicon’s annualized return on average assets and return on average equity for the three months ended September 30, 2026, were 1.12% and 14.05%, respectively.
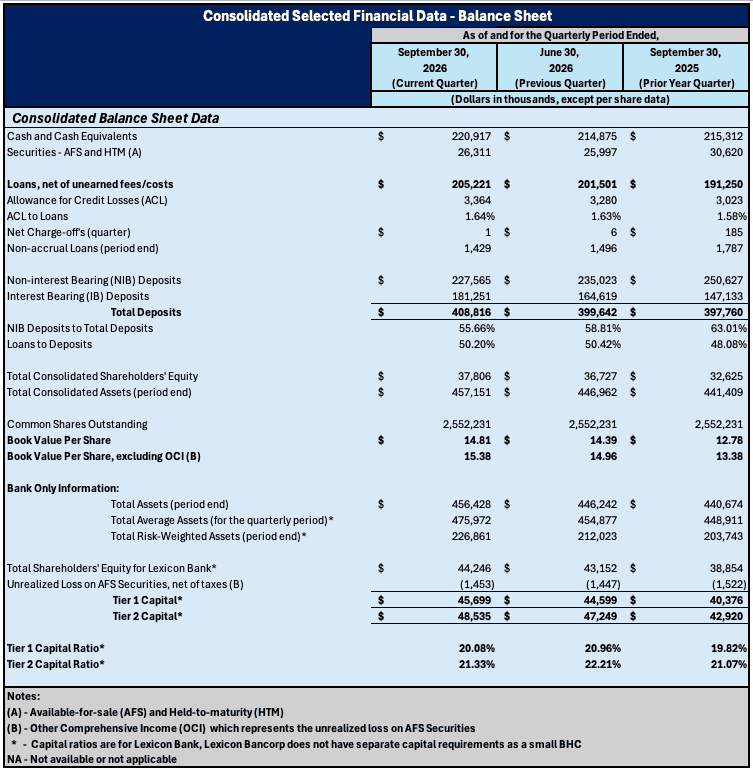
Loans, net of fees, increased to $205.2 million as of September 30, 2026, reflecting net origination of $3.7 million for the quarter. Net loans grew $14.0 million or 7.31%, from September 30, 2025. The loan portfolio continues to perform well, with nonaccrual loans totaling $1.4 million at September 30, 2026. The allowance for credit losses to total loans was 1.64% on September 30, 2026, compared to 1.58% on September 30, 2025.
Total deposits were $408.8 million on September 30, 2026, with non-interest-bearing deposits representing 55.7% of total deposits. We remain focused on building relationships, many of which are primarily deposit-focused, and utilizing third parties to expand FDIC deposit insurance coverage for larger relationships when desired.
Our loan-to-deposit ratio was 50.2% as of September 30, 2026. We continue to leverage our deposit base through the origination of loans, seeking to move the ratio higher over time to serve the needs of businesses in Southern Nevada and to increase earnings.
We held cash and cash equivalents of $220.9 million, or 54.0% of total deposits, on September 30, 2026. Additionally, we have combined unused lines of credit totaling approximately $106.1 million, or 25.9% of total deposits, on September 30, 2026. The combined cash and cash equivalents and unused lines of credit represent 80.0% of total deposits. This combination of liquid assets and available resources provides a strong liquidity position for our clients when needed.
Consolidated shareholders’ equity was $37.8 million on September 30, 2026, compared to $32.6 million on September 30, 2025, driven by net income and a decrease in the net unrealized losses on available for sale (“AFS”) securities by $70 thousand, which totaled $1.45 million on September 30, 2026, compared to $1.52 million a year ago.
Lexicon Bank’s Tier 2 Capital Ratio was 20.08% (10% required to be well-capitalized), Tier I Capital Ratio was 21.33% (8% required to be well-capitalized). Tier 1 and Tier 2 Capital totaled $45.7 million and $48.5 million, respectively, on September 30, 2026.
As of September 30, 2026, Lexicon’s consolidated total assets were $457.1 million, an increase of $15.8 million from September 30, 2025, driven by the growth in deposits used to fund the increase in the loan portfolio and on-balance sheet liquidity.
ABOUT LEXICON BANCORP
Lexicon Bancorp was established in July 2023 to become the bank holding company for Lexicon Bank. Founded in 2019, Lexicon Bank is Southern Nevada's community-focused banking partner. LexiconBank provides personal, comprehensive banking services to business and individual banking clients, emphasizing creating and nurturing long-term relationships. By providing personalized services to all clients, Lexicon Bank helps to foster Southern Nevada's economy and community—ultimately helping to grow and develop the region's local businesses. Lexicon is redefining banking as it should be in Southern Nevada by creating a concierge-like experience for businesses, regardless of size. LexiconBank is located in Tivoli Village at 330 S. Rampart Blvd., Suite 150. The Bank is open from 9 A.M. to 5 P.M. Monday through Friday and 9 A.M. to 12 P.M. on Saturdays. Clients can contact us by phone at 702.780.7700 or online at lexiconbank.com. Follow us on Facebook, Instagram, LinkedIn, and X. Lexicon Bank is member FDIC.
This press release includes “forward-looking statements,” as such term is defined in the Private Securities Litigation Reform Act of 1995. Forward-looking statements are based on the current beliefs of the Company’s Board and executive officers (collectively, “Management”), as well as assumptions made by and information currently available to the Company’s Management. All statements regarding the Company’s business strategy and plans and objectives of Management of the Company for future operations are forward-looking statements. When used in this press release, the words “anticipate,” “believe,” “estimate,” “expect,” and “intend” and words or phrases of similar meaning, as they relate to the Company or the Company’s Management, are intended to identify forward-looking statements. Although the Company believes that the expectations reflected in such forward-looking statements are reasonable, it can give no assurance that such expectations will prove to be correct. Important factors that could cause actual results to differ materially from the Bank’s expectations (“cautionary statements”) are the effects of the COVID-19 pandemic and related government actions on the Company and its clients, loan losses, changes in interest rates, loss of key personnel, lower lending limits and capital than competitors, regulatory restrictions and oversight of the Company, the secure and effective implementation of technology, risks related to the local and national economy, the Company's implementation of its business plans and management of growth, loan performance, interest rates, and regulatory matters, the effects of trade, monetary and fiscal policies, inflation, the effects of natural disasters, and changes in accounting policies and practices. Based upon changing conditions, if any one or more of these risks or uncertainties materialize, or if any underlying assumptions prove incorrect, actual results may vary materially from those described as anticipated, believed, estimated, expected, or intended. The Bank does not intend to update these forward-looking statements.